How Small Business Owners Should Choose Legal Help After a Crash
Suppose you run a two-person landscaping company. A week after a rear-end collision, a shoulder injury still prevents you from lifting equipment. Bookings are cancelled and client messages go unanswered, but you have no regular pay stub showing what the injury cost. When choosing a lawyer, look for someone who can explain how to document that interruption.
This guide provides general educational information for US self-employed owners, not advice about a particular claim. Rules differ by state, so consult a lawyer qualified to advise on the law that applies to your crash. New Jersey and Texas appear below as examples.
Key takeaways
- Check relevant experience, including work with owners whose earnings vary each month.
- Ask for an evidence plan that fits your business records.
- Understand the written agreement, including fees, expenses, and who the client is.
Start With Relevant Experience
The American Bar Association frames the first consultation as a hiring decision and reminds prospective clients that they are the ones doing the hiring. Bring questions, take notes, and compare answers from more than one firm.
Relevant cases. Ask whether the lawyer has represented self-employed people whose income does not arrive in regular paychecks. How were those cases documented? What challenges did they present? Advertising alone cannot establish this experience. Also ask what happens if settlement talks fail and whether the same lawyer would take the case to court.
Independent checks. Check official licensing records rather than relying on testimonials. The State Bar of Texas provides an online attorney profile showing a lawyer's license status and any public disciplinary history. Other states have their own bar or court records. Whichever firm you consider, check the record of the lawyer who would handle your case.
Your point of contact. Ask who will work on your file day to day, how often you will hear from them, and how updates arrive. If your crash happened in Union, New Jersey, you could speak with an accident lawyer at Garces, Grabler & LeBrocq, a local firm. Its Union page describes pursuing compensation from negligent drivers for accident-related losses. That is the firm's service description, not independent evidence of results, so use the consultation to ask how it would approach your circumstances.
Ask How They Would Prove Your Income Loss
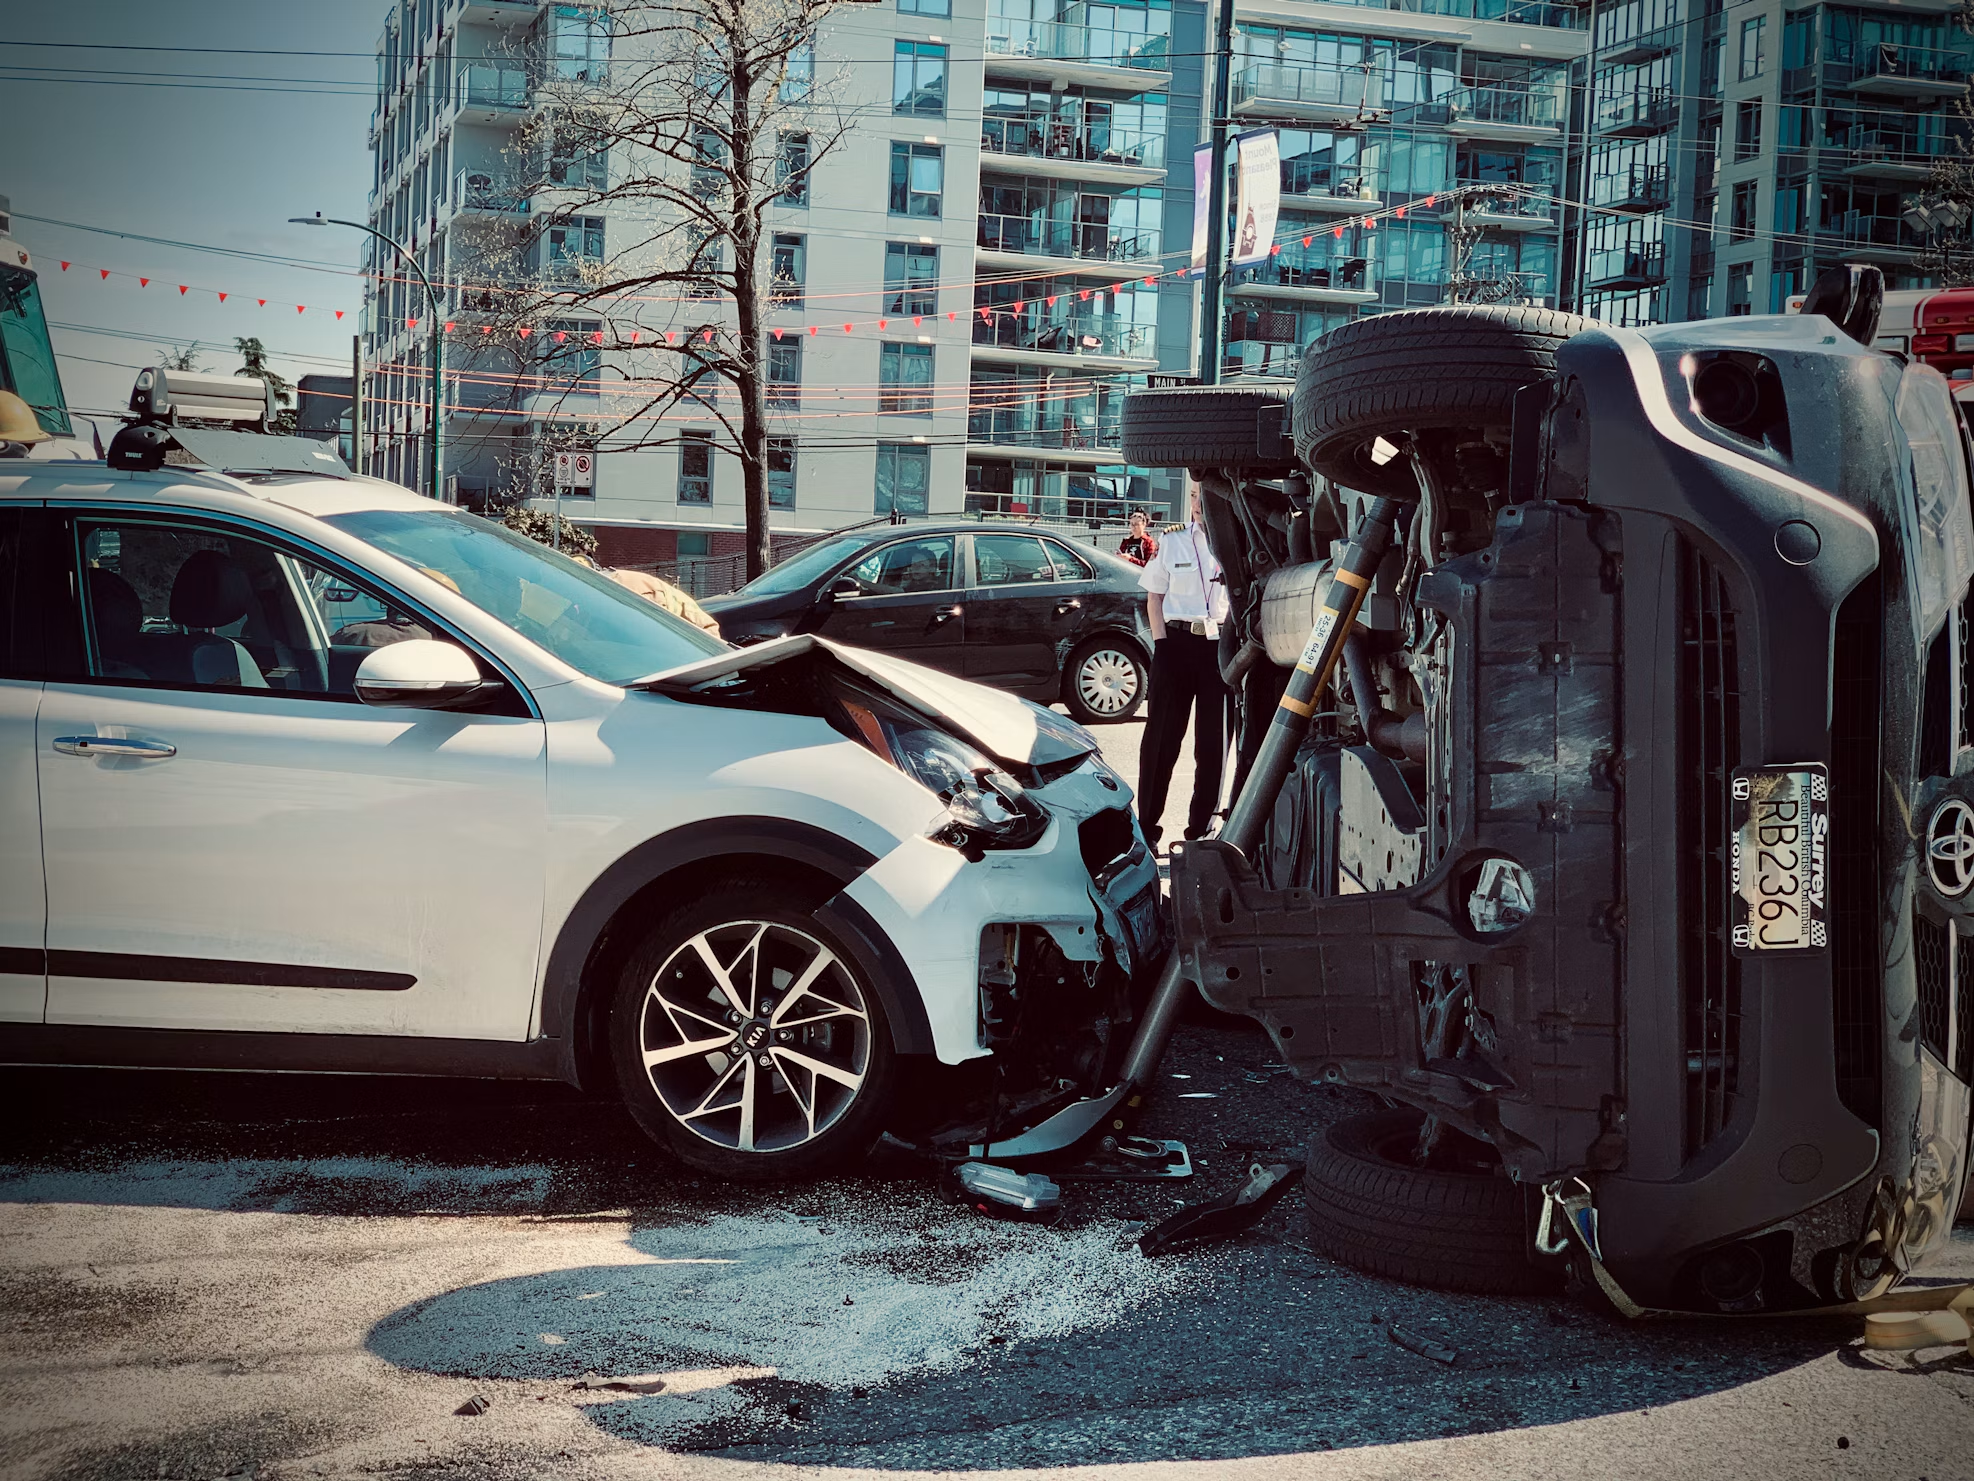
If you don't receive regular pay stubs, ask how the lawyer would use business records to assess self-employed car accident claims and lost income. A useful answer should explain which records matter, what is missing, and how the injury affected your ability to work.
Show your normal earnings. A June 2026 Georgia guide from the Millar Law Firm identifies business records and tax returns as evidence of self-employment income. IRS recordkeeping guidance also calls for a summary of business transactions. Neither source establishes what you can recover in your state.
Before any consultation, gather available tax returns, invoices, contracts, bank statements, and profit-and-loss reports. If your work is seasonal, bring enough history to show the pattern and ask whether the lawyer needs more.
Explain the interruption. Alongside your earnings history, gather records of work you could not do. Booking calendars, cancellation messages, emails declining work, and invoices for replacement help can give the lawyer details to assess. Medical records describing work restrictions can help connect the injury to the interruption.
The hypothetical landscaper might bring cancelled bookings, texts from clients who went elsewhere, and invoices from a contractor hired to finish a job. These records do not guarantee reimbursement, but they help explain what changed after the crash.
Separate the numbers. A Michigan guide from Khamo Law notes that business revenue and the injured owner's personal income are not always the same. Ask how the lawyer would distinguish money billed from what you personally earned, and how they would assess business expenses that continued while you could not work.
Explain your business structure, too. A sole proprietor, a single-member LLC, and a corporation with staff may raise different questions about whose losses are being assessed. Ask whether any claim belongs to you, the company, or both rather than assuming your injury creates a separate claim for the business.
Evidence for future financial losses and earning capacity often relies on professional reports. Ask whether an accountant or another professional would be needed to explain your figures, especially if the injury may affect your ability to earn in the future. For a collision in Fort Worth, Texas, Stogner Trial Law's Car Accident Lawyer page says the firm consults medical experts and economists to document current and future losses, so ask any firm you meet how it would use such professionals in your case.
Check the Proposed Agreement
Some firms advertise a free consultation, while others publish a no-fee-unless-we-win statement. These statements describe different aspects of cost. Neither explains every possible fee or expense, so request the full written terms before agreeing to representation.
Who is being represented. Legal ethics guidance on engagement letters stresses identifying every individual and entity being represented. Ask whether the client is you, your business, or both. The agreement should make clear whose interests the lawyer represents, what work is included, and what falls outside it.
Fees versus expenses. The American Bar Association explains that under a contingency arrangement, clients may still be responsible for case expenses separately from the lawyer's fee. These can include court filing fees and the cost of depositions, which involve questioning witnesses under oath.
Ask how the fee is calculated, when expenses are deducted, and who pays those expenses if there is no recovery. Request a worked example showing deductions from a hypothetical settlement. Check that the written agreement matches the explanation.
What happens next. Before agreeing to representation, ask who would handle your case and what the proposed agreement covers.
Bring your policy documents and explain any business use of the vehicle. The Texas Department of Insurance advises checking whether a policy covers how you use your car and whether exclusions apply. Ask about coverage rather than assuming it, and check your policy's notification and cooperation requirements while you choose representation.
Also ask how unresolved treatment and losses would be addressed before you sign a settlement release. The Texas Department of Insurance advises talking to your doctor about future medical treatment before signing. Tell the lawyer if your recovery or ability to return to work remains uncertain.
FAQs
What if I do not receive pay stubs?
Bring the business records you have, including tax returns, invoices, bank statements, and transaction summaries. Ask which records the lawyer would use and what additional evidence your circumstances require.
What if my income changes each month?
Bring records showing seasonal highs and lows. Ask how the lawyer would assess those patterns and distinguish business revenue from personal earnings. Avoid assuming that a single averaging formula will apply.
Does a free consultation mean the case is free?
No. It covers the initial meeting, not the cost of representation. Under a contingency arrangement, case expenses may remain separate from the lawyer's fee, including if there is no recovery. Check what your agreement says.
How soon should I seek advice?
Seek advice promptly so a qualified lawyer can identify the deadlines that apply. While arranging a consultation, preserve business and accident records and check your insurer's notification requirements.