How a Bookkeeping Service and CFO Advisory Services Work Together to Support Business Growth
Most small business owners know their books need to be accurate. Fewer realize how much a dependable bookkeeping service shapes every major decision that comes later. When transactions are recorded correctly, accounts are reconciled, and reports arrive on time, an owner can see how the business is really performing instead of guessing.
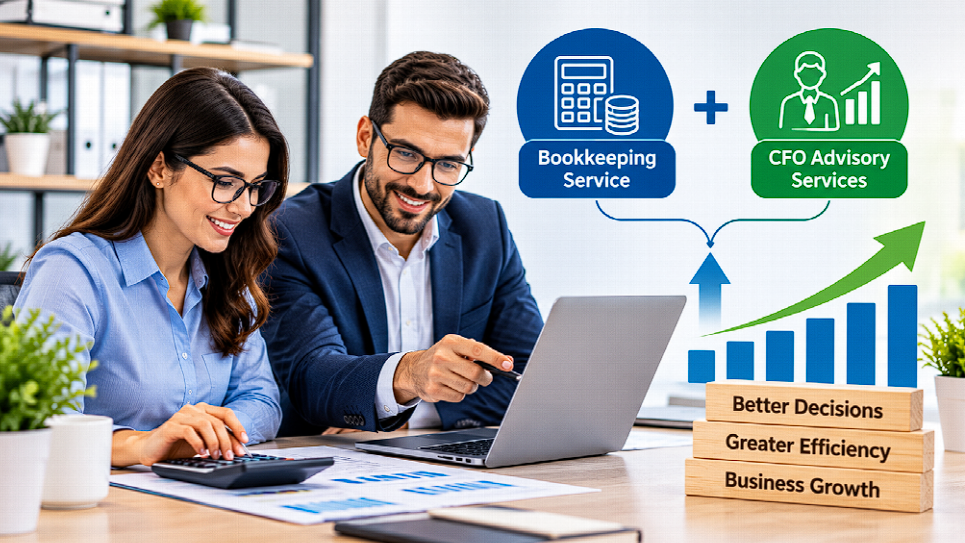
Accurate records are only the starting point, though. Once the numbers are reliable, the next question is what to do with them. That is where CFO advisory services come in. A CFO advisory services engagement takes the financial data a business already produces and turns it into forecasts, budgets, and guidance for decisions about hiring, pricing, spending, and growth.
The two functions are often bought separately, and sometimes from different providers. That can work, but it helps to understand how they connect. Bookkeeping answers the question “what happened?” Advisory work answers “what should we do next?” Each is far more useful when the other is in place.
What Bookkeeping Delivers
Bookkeeping is the ongoing, detailed record of a company’s financial activity. A solid process typically includes:
- Recording and categorizing income and expenses
- Reconciling bank, credit card, and loan accounts every month
- Tracking invoices owed to you and bills you owe
- Maintaining a consistent chart of accounts
- Producing monthly financial statements
- Keeping documentation organized for tax preparation
The value is consistency. A business that closes its books on a regular schedule can spot problems early, such as duplicate charges, unusual swings in expenses, or customers who are paying late. It can also answer basic questions quickly, like how much profit was earned last quarter or how much cash is available for payroll.
What CFO Advisory Delivers
CFO advisory work is forward looking. Instead of recording the past, it uses the past to plan the future. Depending on the scope, an advisor may help with:
- Annual budgets and rolling forecasts
- Cash flow projections that show tight months before they arrive
- Margin and profitability analysis by product, service, customer, or job
- Key performance indicators that connect financial results to operations
- Financial models for hiring, equipment purchases, or expansion
- Lender and investor reporting
Advisory support is often part time. Many companies do not need a full-time finance executive, but they do need senior financial judgment on a regular schedule. A defined cadence of meetings, reports, and planning sessions gives owners access to that judgment without the cost of a permanent hire.
Why the Two Work Best Together
An advisor can only be as accurate as the data in front of them. If reconciliations are weeks behind or expenses are coded inconsistently, a forecast built on those numbers will mislead. That is why many advisors start an engagement by reviewing the quality of the books before building any models.
The reverse is also true. A well-kept set of records that nobody interprets leaves value on the table. Owners may know their balance, but not whether margins are shrinking, whether growth is consuming too much cash, or whether a planned purchase is affordable.
When both functions are coordinated, several practical benefits follow:
- Faster, more reliable reporting. The people reviewing the numbers understand how they were produced.
- Fewer surprises. Forecasts are updated with real results each month, so gaps show up early.
- Clearer tax planning. Current records and projections help owners make decisions before year end rather than after.
- Less duplicated effort. Questions about a transaction do not bounce between unrelated providers.
Signs It Is Time to Add Advisory Support
Many businesses start with bookkeeping alone and add advisory work later. These signals suggest the time has come:
- Your business is profitable on paper but regularly short on cash.
- You cannot say which customers, products, or jobs produce the best margins.
- You are planning to borrow money, raise capital, or sell the company.
- You are making hiring or equipment decisions without a financial model.
- Reports arrive, but no one explains what they mean.
- Growth has made your old tracking methods unreliable.
If two or three of these apply, the cost of continuing without guidance is probably higher than the cost of getting it.
How to Evaluate Providers
Whether you are hiring for bookkeeping, advisory work, or both, a few questions separate strong providers from weak ones.
What is included? Ask for a clear list of deliverables, meeting frequency, and response times. Find out what costs extra, such as cleanup of past records or additional reporting.
Do you understand my industry? Construction companies need job costing. E-commerce businesses face inventory and sales tax issues. Healthcare practices manage insurance receivables. Industry knowledge shortens setup and reduces errors.
What software do you use? Confirm compatibility with your accounting platform and ask how you will access reports. You should keep ownership of your data.
How do you protect information? You are sharing bank access and payroll details. Ask about encryption, secure file sharing, and access controls.
How do you handle messy records? If your books are behind, ask how a catch-up project is scoped, priced, and scheduled before ongoing service begins.
Who will I talk to? Find out who your day-to-day contact is and who is responsible for advisory conversations.
Preparing for a Strong Start
You can make onboarding smoother by gathering a few items in advance:
- Bank and credit card statements for the period under review
- Prior-year tax returns
- Payroll reports and tax filings
- Loan statements and records of major asset purchases
- Access to your accounting software
Be candid about the state of your records. A provider who knows the full picture can scope the work accurately and avoid surprises.
It also helps to decide what you want to learn from the numbers. Examples include which service line is most profitable, how much cash you need to carry through a slow season, or whether you can afford a new hire next quarter. Clear questions lead to more useful reports.
The Bottom Line
Reliable bookkeeping gives a business an accurate record of where it has been. Advisory support helps it decide where to go. Used together, they replace guesswork with a steady rhythm of clean data, regular review, and informed decisions. Owners who build that foundation early are better prepared for growth, financing, and the unexpected, and they spend less time worrying about numbers they cannot trust.