Using Specialized Insurance Technology to Improve Risk Assessment
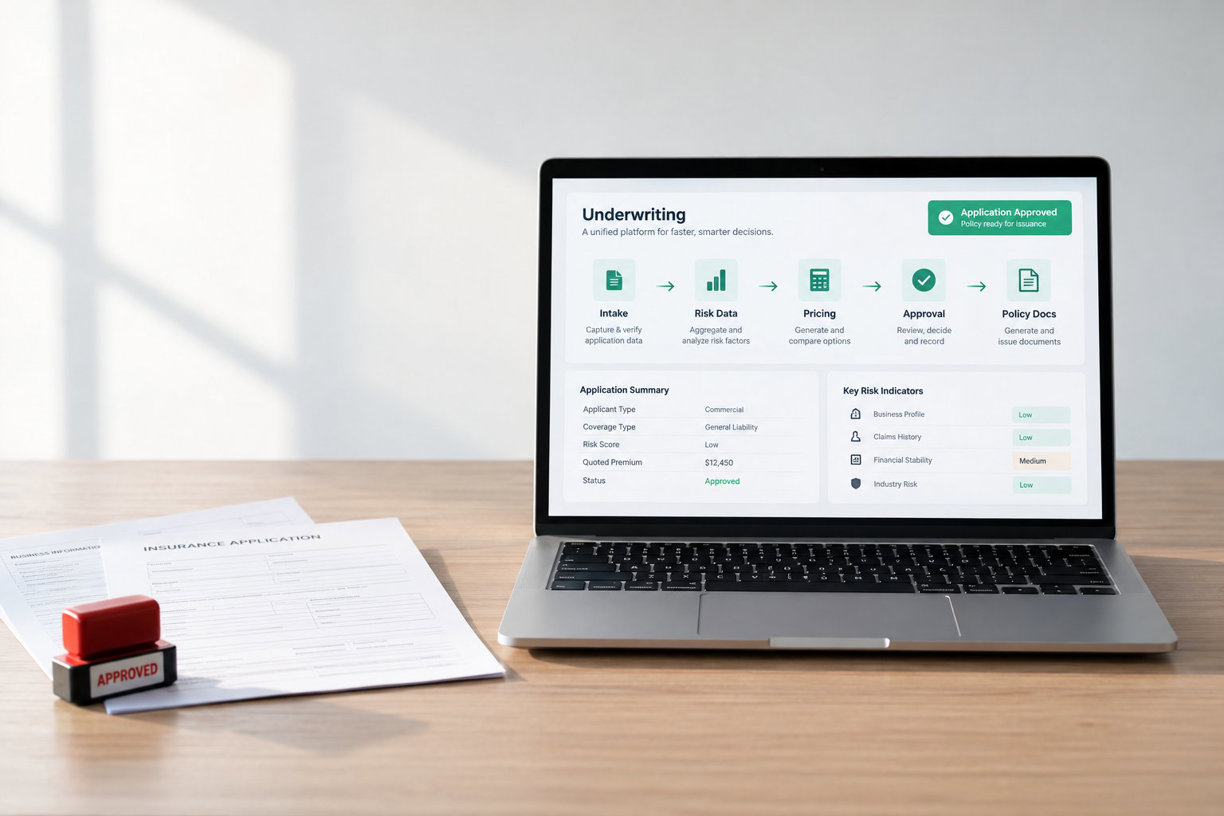
Increasing volatility, quicker decision cycles, and growing regulatory requirements are forcing insurers and business policyholders to rethink how they manage risk. Traditional risk assessment can struggle to keep pace with the volume and complexity of information now at play. As insurers face tighter margins and businesses expect faster responses, the demand for robust systems has increased. The right technology can help turn risk assessment from a reactive process into a more proactive one, benefiting both underwriters and their clients.
Defining better risk assessment
Effective risk assessment today is not just about identifying hazards or threats. It means delivering consistent evaluations, enabling rapid turnaround, and maintaining transparent documentation for regulatory or audit purposes. Modern tools focus on creating clear links between a client’s exposures, risk controls in place, and the effect those factors have on pricing and underwriting capacity. This clarity allows insurers to justify their decisions and enables policyholders to understand how their risk profile shapes their premiums or coverage options.
For example, when an insurer can systematically link a client’s investments in security systems or updated protocols to lower risk scores and improved insurance terms, both parties benefit. These connections become especially important when dealing with complex risks in industries like manufacturing, construction, or logistics, where multiple variables affect outcomes. In a manufacturing scenario, electronic documentation of safety upgrades can help underwriters quickly verify compliance and adjust terms, rather than relying on manual records and slow correspondence.
Inputs that enhance risk-based decisions
The foundation of sound risk assessment starts with internal data. Maintaining clean client records, comprehensive exposure histories, and accurate claims patterns sets the stage for reliable decision-making. Errors or gaps in client information can undermine the assessment process, leading to delays or mispriced coverage.
Practical examples include triaging new submissions using automated checklists to flag incomplete or inconsistent information, reducing the time spent on back-and-forth with brokers or clients. For instance, capturing detailed exposure data during the onboarding process allows for faster premium calculations and more precise risk segmentation. A commercial underwriter reviewing property insurance might reference a standardized loss history report to confirm eligibility before moving forward with coverage terms.
Beyond internal data, external indicators add critical context. Industry-specific benchmarks give you a sense of where a business stands relative to its peers, while third-party risk signals, such as supplier creditworthiness or weather alerts, allow for dynamic adjustments. For risks that change frequently, real-time feeds (like telematics or regulatory updates) can provide timely warning of material changes. An insurer handling a fleet insurance policy, for example, might integrate telematics data to monitor driver behavior and immediately reassess risk pricing following a series of speeding incidents.
Documentation is another essential element. When an organization keeps thorough records not only of decisions, but also of the reasoning and evidence behind them, it reduces the need for rework. Audit trails become more reliable, easing the burden of compliance and helping explain decisions when disputes arise. For many providers, commercial insurance software enables documentation and audit trails by automatically cataloging all underwriting actions and supporting materials related to each submission, which is especially important in regulated markets or when managing complex accounts.
Capabilities that drive stronger outcomes
One significant shift has been the move from free-form, narrative data entry toward structured capture. When underwriters use standard fields and checklists, important details are less likely to be missed, and the information is easier to analyze later. Many systems also embed automated rules and scoring models, helping standardize routine cases while still allowing experienced staff to step in when unique factors are present. For example, automation can route a straightforward small business policy directly to binding, while a flagged submission with unusual risk factors is escalated for manual review by a specialist.
Scenario testing is increasingly valuable at the portfolio level. For instance, changing an underwriting rule or adding a new risk variable can be modeled to see its effect on potential loss ratios or capital demands. This approach enables insurers to balance growth with risk appetite in practical terms, rather than relying solely on historical data or assumptions. As an example, an insurer might test the impact of tightening fire safety requirements within a commercial property book to visualize how it would affect both loss prevention and premium volumes.
Equally important is maintaining transparency. Decision trails built into systems help with internal governance and make it easier to review underwriting choices if questions arise later. These audit-friendly processes help insurers demonstrate sound judgment, a growing necessity in regulated markets.
Operational benefits for business teams
When risk assessment processes are integrated into business systems, there can be immediate operational benefits. Fewer manual bottlenecks mean applications move more quickly through underwriting, and underwriters can spend less time chasing information. Faster referral workflows become possible, leading to reduced turnaround time even on complex cases. For example, automated referrals for specific risk parameters allow large commercial accounts to be reviewed by senior underwriters without disrupting the flow of standard submissions.
Clarity in risk decisions also supports better coordination between underwriting, claims, and sales teams. Everyone understands how and why key choices are made. This alignment reduces duplication of work and clarifies accountability, freeing teams to focus on portfolio growth and customer relationships.
Pitfalls to avoid and lessons learned
While improved technology has great potential, it is not without risks. One common pitfall is overfitting models, designing them so closely to historical data that they fail when conditions change. Another issue involves neglecting data lineage, which undermines trust in outputs. Fragmented toolsets can prevent information from flowing smoothly across the organization, leading to inconsistent decisions and wasted effort.
The rise of complex algorithms has also made "black box" decisions more common, raising concerns about model risk and lack of explainability. When staff cannot explain or challenge the basis of a decision, trust in both the tool and the outcome erodes. Regular model reviews and keeping expert oversight in the loop are essential countermeasures.
Practical implementation for stronger results
Starting small helps. Many firms choose one line of business or risk segment, define clear decision criteria, and align data responsibilities before expanding. Measuring the quality of risk assessment processes involves tracking decision accuracy and cycle times to ensure improvements are meaningful.
Above all, treat risk assessment as a business system, not a technical add-on. When processes and data align for transparency and efficiency, insurers gain the confidence to make faster, better-grounded decisions without sacrificing risk controls or compliance requirements.